Akcie společnosti FirstGroup (LON:FGP) vzrostly o 3 % poté, co dopravní společnost oznámila akvizici společnosti Tetley’s Motor Services Limited, provozovatele autobusové dopravy se sídlem v Leedsu.
Akvizice přináší do vozového parku FirstGroup 55 autobusů a velkou vozovnu v centru Leedsu, která sousedí se stávajícím zařízením First Bus. Společnost Tetley’s Coaches vykázala za 12 měsíců končících 31. března 2024 zisk před úroky a daněmi (EBIT) ve výši 1,4 milionu liber při tržbách 5,3 milionu liber.
Tetley’s provozuje různé dopravní služby, včetně služeb pro školy, univerzity, kyvadlové dopravy na pracoviště a soukromé pronájmy v Leedsu a West Yorkshire. Významná část smluvního portfolia společnosti byla nedávno obnovena, což zajišťuje stabilitu podnikání. Ian Tetley, generální ředitel společnosti Tetley’s Coaches, zůstane ve společnosti i během její integrace do First Bus.
„Sérii akvizic autobusových společností ze strany FirstGroup vnímáme příznivě, a proto vítáme další transakci, která zvýší marži a dále diverzifikuje tržby z autobusové dopravy. Domníváme se, že FirstGroup obecně zaplatila nižší transakční násobky než naše ocenění i tržní ocenění autobusové dopravy, což znamená, že tyto akvizice nejsou závislé na potenciálních synergiích, které by mohly zvýšit zisk,“ uvedli analytici RBC.
Tato akvizice představuje další strategický krok společnosti FirstGroup k rozšíření svých dopravních aktivit prostřednictvím cílených akvizic na britském trhu.
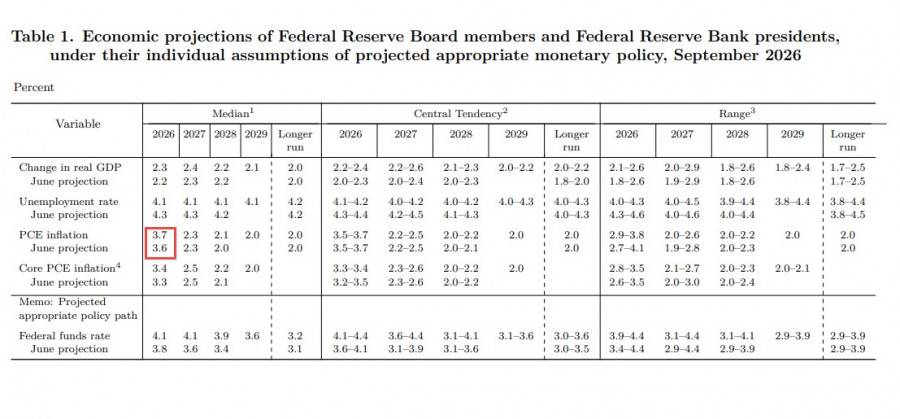
On September 16, the Fed raised its policy rate by 25 basis points to 3.75–4.00%. This was the first increase since July 2023. The updated dot plot showed the median year-end rate forecast rising from 3.8% to 4.1%, implying at least one more hike.
On paper, that should have supported the US dollar. But the market didn't buy the hawkish signal. By the next day, CME FedWatch futures showed parity: the odds of a rate hold on October 28 and another hike were roughly equal.
The reason lies in Fed Chair Kevin Warsh's rhetoric: he deliberately declined to give forward guidance and did not promise either a continued tightening cycle or a pause. In an environment of still-elevated inflation and a slowing economy, that ambiguity is read by markets as a clear constraint on policy flexibility.
The updated projections revised core PCE inflation higher, acknowledging that inflation has proven more persistent than expected, but growth forecasts were also nudged up. The Fed still does not appear to subscribe to a stagflation scenario.
A second blow to the dollar came from oil. On September 21, Brent fell to $101.71, and WTI dipped below $100 to $98.15, marking the lowest levels since September 10 and the fourth straight day of declines. The catalyst was renewed optimism about a diplomatic settlement. Lower oil eases price pressure and reduces the impetus for further rate hikes. Risks remain: Iran again issued a seven-point list of conditions, and the secretary of Iran's Supreme National Security Council warned of a "decisive battle" if the US rejects those conditions. Over the weekend, the Houthis launched a ballistic strike on Riyadh — the first attack on Saudi Arabia's capital since the conflict began.
Oil has become the dollar's primary barometer. If talks yield results and oil continues to fall, the dollar will stay under pressure. If negotiations fail and oil returns above $110, the dollar would likely get a fresh bid.
As of September 15, net long positions in DXY futures plunged from 17,025 to 10,593 contracts, notching a 38% drop in one week. Speculators began aggressively unwinding dollar long positions even before the Fed meeting. The market had already priced in that, even if the hike took place, it would be the last one. When the Fed actually raised rates, there were no new dollar buyers left — everyone who wanted to buy had already exited.
The scope for further dollar selling is limited. There is not much left to sell. However, a new catalyst will be needed to drive a sustained rally.
Over the coming weeks, the dollar is likely to remain under pressure. A "hawkish pause" from the Fed, falling oil, and the already-sized-back liquidation of long positions all work against the dollar. Over a longer horizon, the outlook will hinge on developments in the Gulf and on whether a stagflation scenario materializes for the US economy.


 コンタクトする